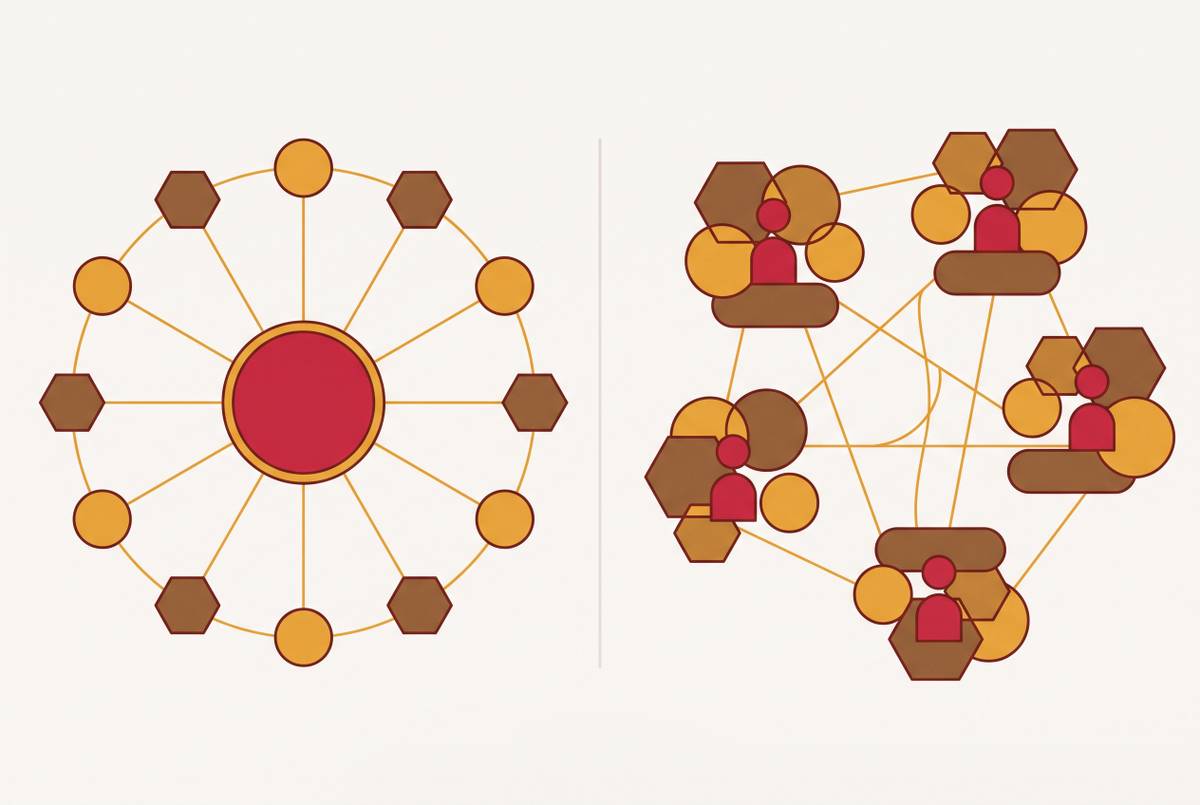
RevOps at PE-Backed vs VC-Backed Companies
PE prioritizes margin discipline while VC demands rapid growth experimentation.
PE and VC both want a company that grows and eventually exits at a higher price than someone paid to get in. Past that shared ambition, the two ownership models pull RevOps in nearly opposite directions, and a practitioner who doesn't recalibrate for which one they're sitting inside will optimize for the wrong thing.
The mechanics explain why. PE firms mostly buy majority or full control of mature companies and run them on a multi-year clock before selling. VC firms take minority stakes in young, unproven companies and think in eight-to-ten year paybacks, a distinction one industry consultant has laid out on a RevOps podcast. A shorter hold compresses how fast RevOps has to prove it's worth the seat at the table. A longer horizon buys room to test things that might not pay off for years. And the value-creation math has shifted too: operational improvement and revenue growth have become the dominant drivers of PE value creation, with revenue growth accounting for a large share of value created in recent exits. RevOps is one of the levers being pulled in that world. It's one of the levers being pulled.
What PE-backed companies ask RevOps to optimize for
Efficiency first, growth second, but never growth alone. PE-backed RevOps teams get judged on margin discipline, deal desk rigor, renewal and expansion tracking, and on whether the company is paying for six tools that do the job of two. Growth for its own sake doesn't impress a sponsor who's going to hand the company to another buyer in three years and needs the books to hold up under diligence.
The Rule of 40 (revenue growth rate plus profit margin should add up to 40 or more) becomes the shared language for growth and profitability, and RevOps is the function that has to report both halves honestly, not just the flattering one. That means stripping out the noise: growth should reflect recurring revenue, not a number inflated by one-time services that won't repeat next year. A score of 45 built mostly on growth tells a buyer something very different than a 45 built mostly on margin, even though the arithmetic is identical. The first company still has room to run. The second one has probably already been optimized to the edge.
Net revenue retention gets watched just as closely, often against a target near 95%, which turns expansion and renewal tracking into a RevOps responsibility rather than something customer success owns quietly on the side. And in most PE-backed portfolio companies, FP&A shapes decisions in real time. It's shaping decisions in real time. RevOps has to speak fluently in EBITDA, gross-to-net, payback period, and unit economics, not just pipeline and bookings.
What VC-backed companies ask RevOps to build
Early-stage VC-backed companies, roughly Seed through Series A, need RevOps to build the basics, including a working HubSpot instance, dashboards showing whether the funnel is moving, and a documented and repeatable go-to-market motion. These engagements tend to run a few months, not years, because the company itself is still figuring out what it's selling and to whom.
By Series B through D, the ask changes shape completely different from before. Now it's multi-region architecture, real attribution modeling, forecasting that holds up as headcount doubles, and constant experimentation on what's actually driving pipeline. Retainers shift from setup work to ongoing optimization, because the system that worked at 20 reps starts cracking at 60.
Speed is the constant across both stages. A venture-backed startup burning through a fresh round can't afford a RevOps engagement that delivers a strategy deck in month four. Value has to show up in weeks. That urgency is reshaping who gets hired for the work: heading into 2026, the dominant model looks like fewer generalist ops hires and more fractional specialists who treat go-to-market like an infrastructure problem, not a slide deck problem. Firms that ship automated workflows and clean CRM data are winning the work that used to go to firms that just wrote recommendations.
Metrics RevOps owns in each environment
A PE-focused RevOps dashboard reads like a finance document: Rule of 40, EBITDA margin contribution, NRR against that 95% target, gross revenue retention (GRR), payback period, gross-to-net revenue, cost-per-tool, and how fast cash actually gets collected.
A VC-focused dashboard reads like a growth document: top-line ARR growth rate, pipeline velocity, stage-by-stage conversion, CAC and CAC payback, attribution by channel, how fast a new rep ramps to full quota. Efficiency metrics are visible here too, but growth metrics dominate the dashboard ahead of them.
The distinction between the two retention metrics affects how PE-backed companies assess whether growth is masking underlying churn. NRR captures how well a company retains and expands revenue from existing customers, upsells included. GRR strips the upsells out and shows retention on its own. PE-backed companies track both because expansion revenue can obscure what is happening at the base retention level. Knowing the base is sound matters even when some accounts are growing fast enough to mask churn elsewhere.
Both environments claim the Rule of 40 as a shared compass, and VC-backed companies chase it just as hard. But the weighting differs. PE sponsors lean harder on the profitability half, because the eventual buyer is going to run the same math and won't be forgiving of thin margins. VC-backed companies routinely tolerate negative margins at the growth stage, a posture that sits uncomfortably with the profitability discipline PE sponsors prioritize.
Equity structure and the executive mandate RevOps reports into
Equity grants tell you who actually holds decision-making power, and the gap is wide. The median initial equity grant to a non-founder CEO at a VC-backed startup runs around 4.8% of fully diluted equity. At a PE-backed company, it's roughly 2.3%, less than half.
The pattern holds down the org chart. Non-founder C-suite executives at VC-backed companies get initial grants averaging around 1% of total equity; at PE-backed companies, that number sits closer to 0.45%. VC executives, in other words, operate with wider authority and a bigger personal stake in the outcome, because they're frequently the genuine decision-makers brought in to run a real growth phase.
PE-backed executives work inside a tighter frame. They report into a majority owner, often one that holds 100% of the company, and that owner's thesis, not an independently empowered C-suite, sets the agenda. A RevOps leader's mandate in a PE-backed company is shaped by the sponsor's priorities for the business before exit. Understand the equity structure and the mandate practically writes itself.
How fractional RevOps fits differently into each environment
Fractional RevOps means a part-time, embedded leader who builds CRM architecture, forecasting systems, pipeline reporting, and standardized sales process, without the company carrying a full-time salary line. Engagements typically run $5,000 to $10,000 a month, against a full-time VP of RevOps salary that can run $251,000 to $315,000 or more annually. For a portfolio company that needs senior-level capability without a permanent headcount commitment, that math is not subtle.
The talent market makes fractional more than a cost decision. Heading into 2026, open RevOps roles outnumber available senior candidates by something like 2.3 to 1, and RevOps leaders at growth-stage companies command $200,000 to $300,000-plus in total compensation when they do get hired full-time. Fractional talent fills the gap when hiring drags on or capital is tight, which describes a large share of both PE portfolio companies and venture-backed startups at any given moment.
Inside PE-backed portfolio companies, fractional RevOps work tends to concentrate on data integrity, tool consolidation, and exit readiness, with deliverables that are concrete and dated: 25 to 30% fewer duplicate CRM records within the first 30 days, CRM adoption above 95% by day 60, pipeline lift of 63% within six months, the kind of numbers a sponsor expects to see in a board deck. Those are the kind of numbers a sponsor expects to see in a board deck. They're the kind of numbers a sponsor expects to see in a board deck.
Commission plan design differences between PE and VC environments
A commission plan is never just a pay mechanism. It's a behavioral lever, and what counts as the "right" behavior depends entirely on who owns the company.
PE-backed plans tend to align variable pay more directly with profitability metrics, connecting sales behavior to the metrics the sponsor watches most closely. Many PE-backed companies go further and tie commission to actual cash collection, not just closed-won bookings, which protects margin by cutting the risk that a "closed" deal never turns into collected cash. Clawback provisions are more common in these environments, because auditability and financial hygiene sit on the board's agenda, not just finance's. And the numbers make clear why sponsors watch this closely: only 51% of Account Executives hit quota in 2024, down from 66% in 2022 according to RepVue, and even after many companies lowered quotas to compensate, close to 77% of sellers still missed. A PE sponsor reviewing that gap isn't going to treat it as a rounding error.
VC-backed plans optimize for a different problem: speed. New hires need a commission structure simple enough to onboard in days during a post-funding hiring surge. Caps on commission are rare, because a cap demotivates the exact reps driving the growth the company is betting on. Pipeline volume, not margin, is the primary target these plans are built to reward. Across both ownership types, though, the design goal converges on the same benchmark: quota attainment somewhere in the 60 to 80% range across the team, a commonly cited benchmark for whether a plan is calibrated correctly rather than too easy or too punishing.
What both environments agree on is discipline in how plans get built and changed: keep them role-specific, separating SDR incentives from AE incentives, review them quarterly, and never make a structural change mid-year that breaks a rep's trust in the plan. Heading into 2026, best practice looks like quarterly tuning of mechanics paired with one annual structural review, nothing more frequent than that on the structural side.
Why spreadsheet-based commission management breaks differently in each environment
Spreadsheets are still the default. Only about 27% of companies have fully automated their end-to-end commission process, and more than 60% of small and mid-size businesses still run commissions in spreadsheets.
The failure mode looks different depending on who owns the company. In a PE-backed business heading toward exit, a spreadsheet has no audit trail, no locked pay periods, and no record of who approved what. That's a liability during diligence, the kind of gap a buyer's finance team flags and prices into the offer.
In a VC-backed company, the spreadsheet doesn't fail on audit grounds, it fails on scale. Going from five reps to twenty-five after a Series A round turns manual commission calculation into a bottleneck that slows down payroll and chips away at rep trust at the exact moment retention matters most. Both failures trace back to the same root cause: for a team of ten or more reps running anything beyond the simplest plan logic, the real monthly cost of running commissions in Excel, counting analyst hours, dispute resolution, error correction, and the audit trail that never existed, typically runs between £1,500 and £4,000, a recurring drain rather than a one-off expense. That's not a one-time cost. It repeats every month the spreadsheet stays in place.